
Table of Contents
10 weeks left
You have 10 weeks left until 2026 is gone forever. And realisically , you have 7 weeks because Thanksgiving and the back half of Christmas takes time off the clock.
We started with 14 weeks. Now we have 10. That is still enough time, but the clock is real.
So far, we covered the 2026 law changes, how to build a tax smart business, and how real estate investors keep more. Today we finish with the year that scares people most: the big income year.
Maybe you sold a business. Maybe a deal paid out. Maybe the business just had a great year. Good news is great. A surprise tax bill in April is not.
Most people find out they had a big year when we prepare the return. By then, every door is closed. Right now, most of them are still open..
Is this your big year?
Run this quick check. If you say yes to even 1, keep reading.
-
Did your income jump? Your 2026 income is a lot higher than 2025.
-
Did you sell something? A business, a rental, land, or stock with a big gain.
-
Did a deal pay out? A big K1, a fund exit, or a refinance with a payout.
-
Did you get a big bonus or commission?
-
Is next year going to be smaller? Retirement, a slower year, or a sale that ends your income.
Now the flip side. Some of you are having a low year. You stepped back from work, the business had a slow year, or you are between deals.
A low year is not wasted. It is one of the best times to plan. Keep reading. The Roth section is for you.
Roth conversions: pay tax now, pay $0 later
Think a low income year means you can skip tax planning? Think again. If you have money in a traditional IRA or 401(k), a low year may be your best chance to save.
A Roth conversion moves money from a traditional IRA into a Roth IRA. You pay income tax on the amount you move this year. After that, the money grows tax free. Follow the rules, and you pull it out tax free in retirement.
There is no income limit on conversions. Anyone with a traditional IRA can do one.
The whole game is timing. You want to pay the tax in a year when your rate is low.
When a conversion makes sense
-
A low income year. Retired early, a slow year, or between deals.
-
A down market. Your account dropped in value. You convert more shares for the same tax.
-
You expect higher rates later. Your income will rise, or you expect tax rates to go up.
When it usually does not
-
Your big year. If you are already in the 32%, 35%, or 37% bracket, converting now often means paying top dollar. Wait for a lower year and make a plan to lower your tax
-
You would pay the tax from the IRA itself. That shrinks what you converted. Pay it from other cash if you can.
Fill the bracket
You do not have to convert it all. Smart planners convert just enough to fill up your current bracket and stop.
Example. A married couple has a low year. Their 2026 taxable income is $150,000. The 22% bracket runs up to $211,400 (2026 IRS brackets). They can convert about $61,000 and stay in the 22% bracket. The tax is about $13,500. That $61,000, plus all its future growth, is now tax free for life.
3 rules to know
-
The deadline is December 31. A conversion counts in the year it happens. You cannot do it in April like an IRA contribution.
-
You cannot undo it. Once it is done, it is done. That is why you plan the number first.
-
It can raise other costs. More income can raise Medicare premiums later and affect other deductions. A plan checks these first.
Timing is the strategy
In Issue 3, we showed how cost segregation turns a rental into a big tax loss. This week, the part most people miss: when you take that loss matters as much as how big it is.
A call I had this week
A client called me Friday. He earns a W2 income, usually $350,000 to $650,000 a year. Last year was slow. This year, 2 big commission checks will push him past $600,000.
His question: “Is it too late to do anything for this year?”
Short answer: no. But the clock is running.
Same deduction, bigger savings
Here is the math I walked him through.
-
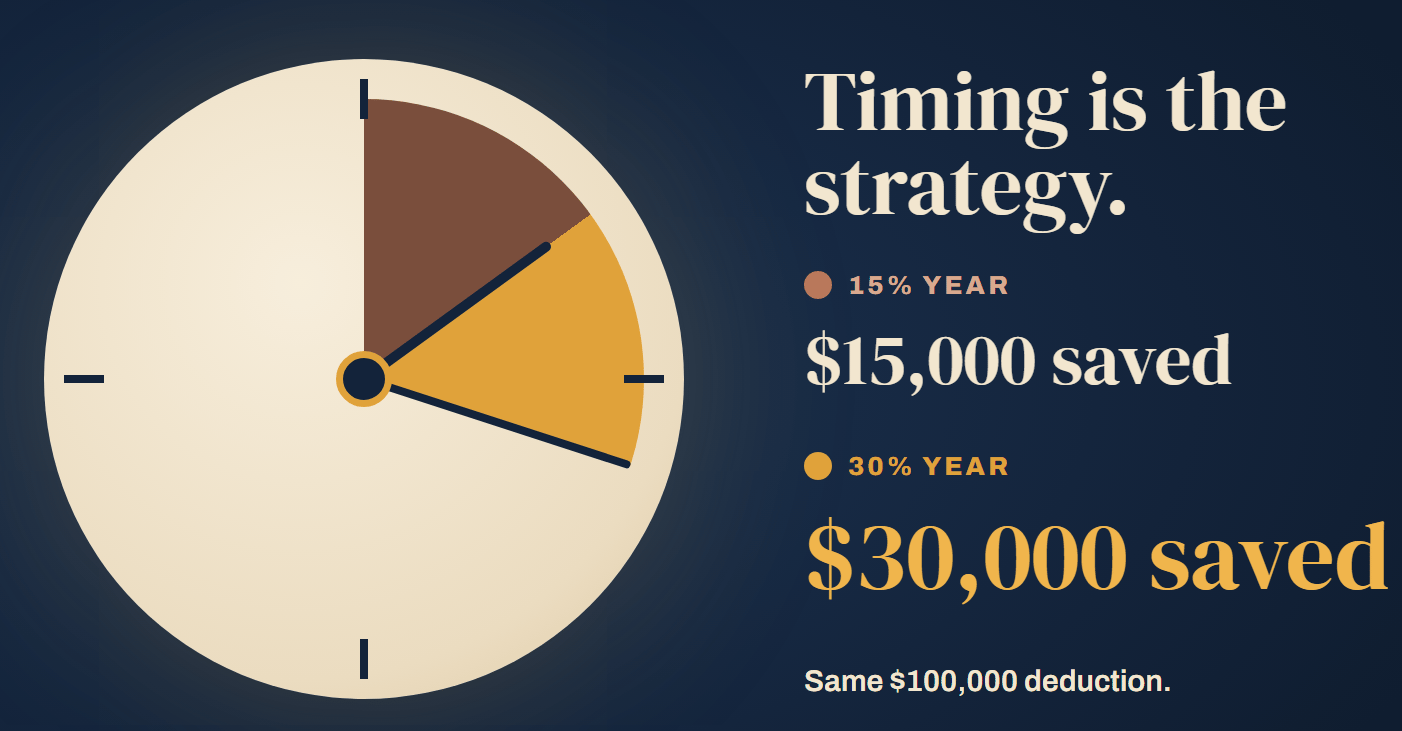
A $100,000 deduction in a 15% year saves you $15,000.
-
The same $100,000 deduction in a 30% year saves you $30,000.
Same deduction. Double the savings. The only thing that changed is the year.

You can choose the year
This is the beautiful part. A cost seg study creates a big loss up front. But that loss does not have to land in the year you buy.
-
You can wait. The study does not have to be done by December 31. It just has to be done before we file the return. If you bought in a slow year, we can even do the study in a later, bigger year and catch up the depreciation then.
-
You can spread it out. You can choose to skip the big first year write off and take it slower when that fits your income better.
If your income swings a lot from year to year, this is a big deal. We put the loss in your highest year, where every dollar is worth the most.
What it looks like
Say you buy a $500,000 short term rental with a mortgage. A cost seg study can create about $100,000 to $125,000 of tax loss in year 1. In a 30% year, that is about $30,000 to $37,500 back in your pocket.
What a real tax plan looks like
Here is the truth most people never hear. A tax return is not a tax plan.
A return looks back. It reports what already happened. By the time we file it, the year is closed and the choices are gone.
A plan looks ahead. It runs your numbers before December 31, while you can still change them.

What happens in a real plan meeting
-
We project your year. We estimate your 2026 income and tax before the year ends. No guessing in April.
-
We find your bracket. We show where your next $1 of income lands and what it costs you.
-
We test the moves. Roth conversion or not? Buy that rental now or next year? Buy equipment or wait? We run each one with real numbers.
-
We pick what works. You get a short list of moves, a dollar amount for each, and a deadline.
-
We check in again. Life changes. A sale closes. A deal pays out. The plan changes with it.
Every strategy in this series (entity changes, retirement plans, cost segregation, Roth conversions, real estate timing) works best inside a plan. Alone, each one is a guess.
A real big year story
Here is the Case Study of a plan we executed for a client making $372k in which we saved them over $55k.

Get a plan before December 31
Most of you work with us at the Compliance level. We prepare your return, get it filed on time, and send you a short video that walks you through it. That is the floor, not the ceiling.
-
Clarity. Everything in Compliance, plus your own Tax Manager, 3 one hour meetings a year, and a written tax projection. You know where you stand before the year closes, not after.
-
Vision. Our most complete level. You get a written tax plan built just for you, plus 6 meetings a year with your Tax Manager. It is built for big years, business owners, and investors.
Only 7 Vision spots are left for Q4. We close them on November 11. We cap the number on purpose, so every Vision client gets our full attention and the best possible service. When the 7 are gone, they are gone.
Want to see what each level includes and what it costs? See our services guide below –
Book a free 30 minute call. We look at your actual return and tell you which level fits.
Last call: win a free Vision tax plan
25 readers have qualified so far for our drawing for a free Vision tax plan. Every qualified referral is another entry.
Entries close today, Saturday, October 24. We announce the winner on Monday, October 26.
Know someone with a big year coming? Send them this issue.
The giveaway is separate from the 10 Q4 Vision spots. Winning the drawing does not take a spot from anyone.
That’s a wrap
That is the end of Tax Plan Series. Here is the whole playbook in 4 lines:
-
Part 1 (Sept 26th): Why these 14 weeks matter, and what changed in the tax law
-
Part 2 (Oct 3rd): Business owners. How to build a tax smart business
-
Part 3 (Oct 10th): Real estate investors and LPs. Depreciation, rentals, and K1s
-
Part 4 (Next Week): Big income years. Roth conversions, Timing Strategies, and what a real tax plan looks like
Each one gives you real moves you can use. No fluff.
Until next week. Your success is our success. Thanks for reading !
Vince & the P&C Team


Leave a Reply